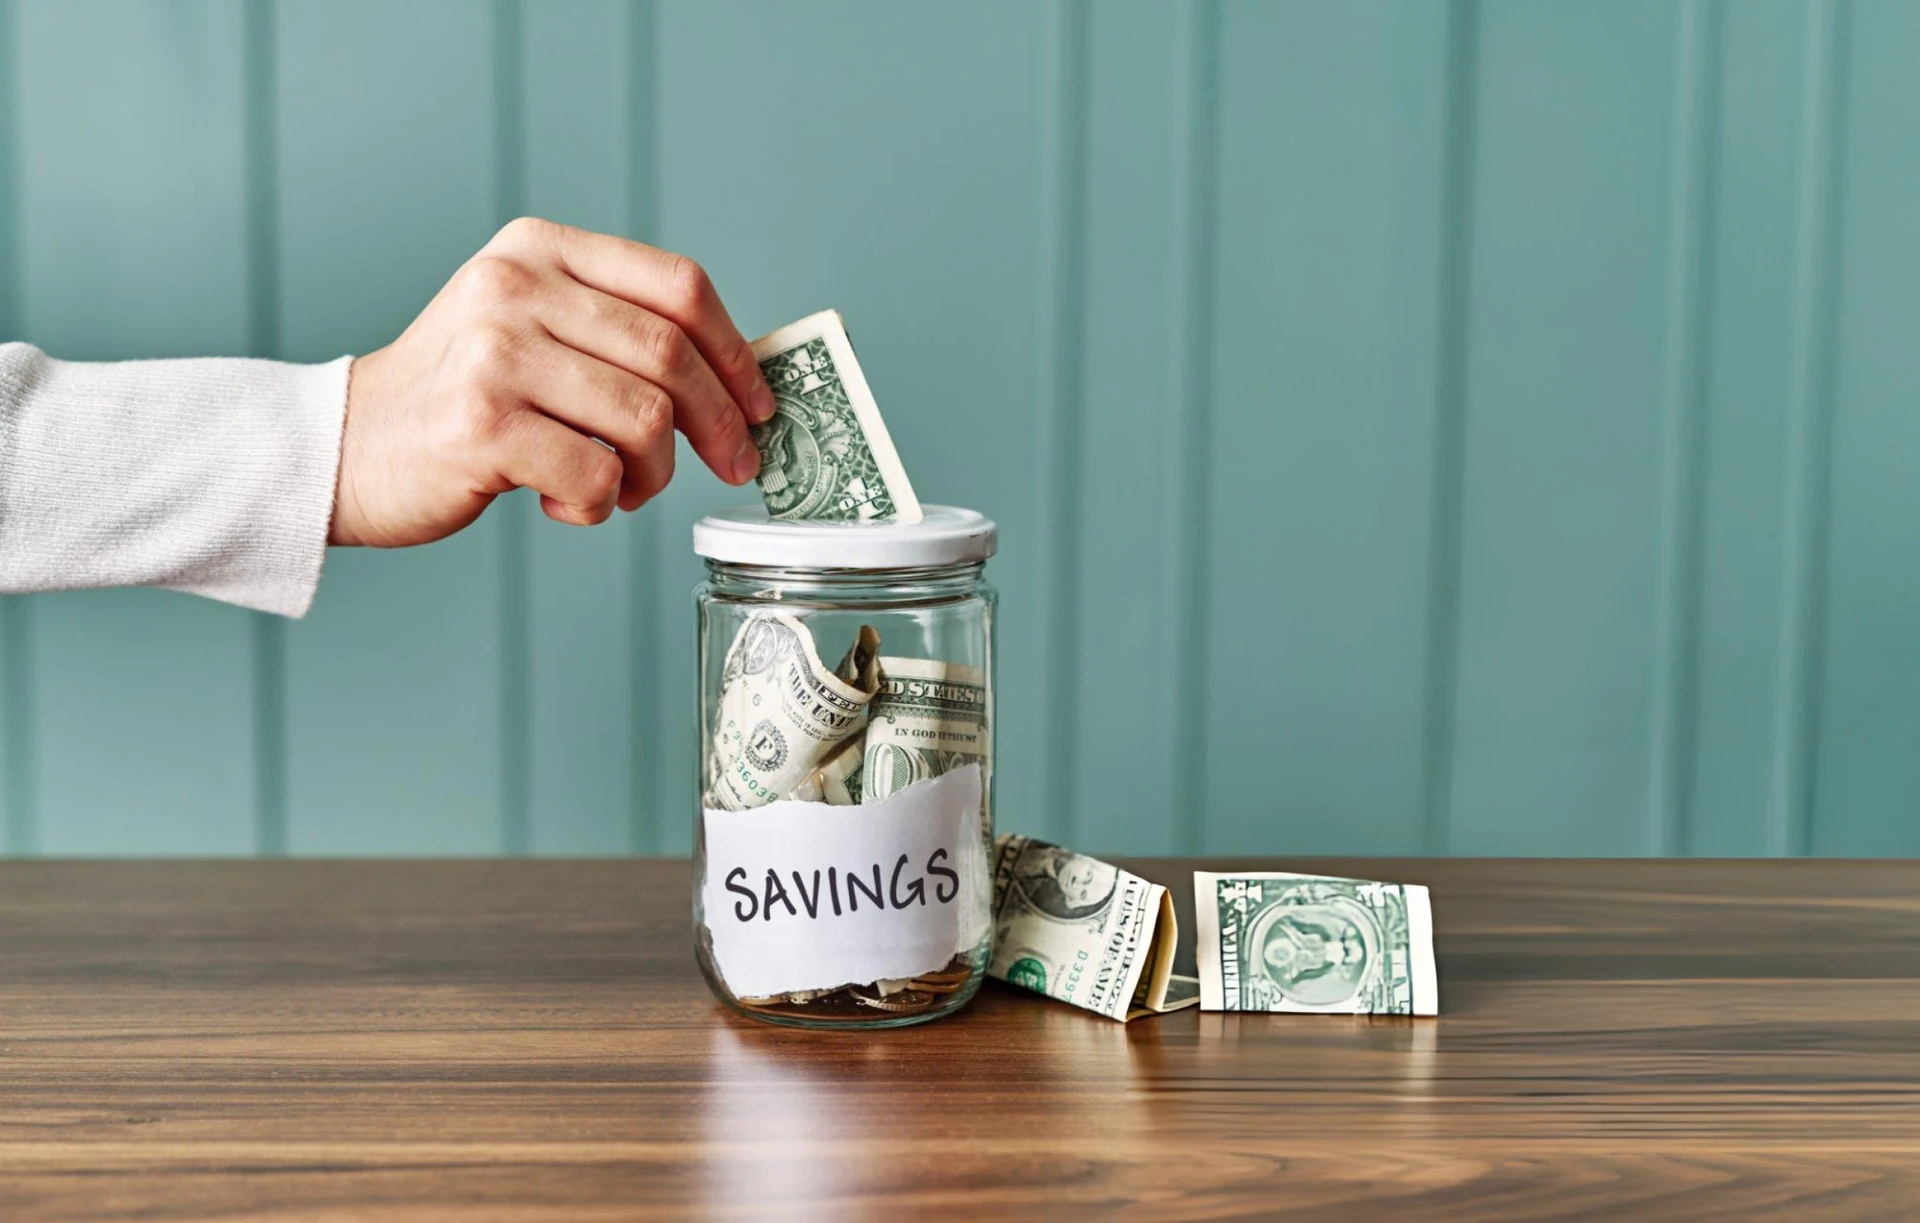
People often treat savings as whatever is left at the end of the month. That leftover is rarely enough, and it is easy to spend. A clearer approach is to name the job each dollar is supposed to do, then give it a place to live.
Name the goal before you name the account
An emergency buffer (repairs, a gap in income, a medical bill) is not the same as a home down payment, a child’s education fund, or a business cash reserve. Mixing them in one bucket makes it easy to “borrow” from the roof fund to cover a weekend, and hard to know whether you are on track.
Write the purpose in plain language: “three months of essential bills,” “replace the car in 2028,” “tax set-aside for the business.” The label matters more than a product name at the start.
Pay the goal first, in a size you can keep
A modest automatic transfer on payday beats an ambitious plan you abandon in week three. If your income varies, set a small floor you can meet in a quiet month, then add extra in stronger months. The point is repetition, not a single large deposit.
We offer savings and current account options for personal banking. Product terms, rates and minimums will be confirmed with official details. This article is about the habit, not a specific yield or promotion.
Keep the spending account and the savings account apart
When savings sit in the same place as everyday spending, the balance looks available. A separate savings account (or a clearly labeled sub-account, when available) creates a pause. That pause is often the difference between an impulse and a decision.
For businesses, the same idea applies to tax and operating reserves. Mixing them with day-to-day payables makes both look healthier than they are.
Review quarterly, not daily
Daily checking of a savings balance can turn a long-term plan into a source of anxiety. A quarterly look is enough for most personal goals: Is the automatic transfer still running? Did the goal change? Do you need to raise or lower the amount?
If you are ready to talk about account options, start with Personal Banking or Contact Us. If cash flow is the tighter constraint, money in and out through the month, Business Banking is the better conversation.